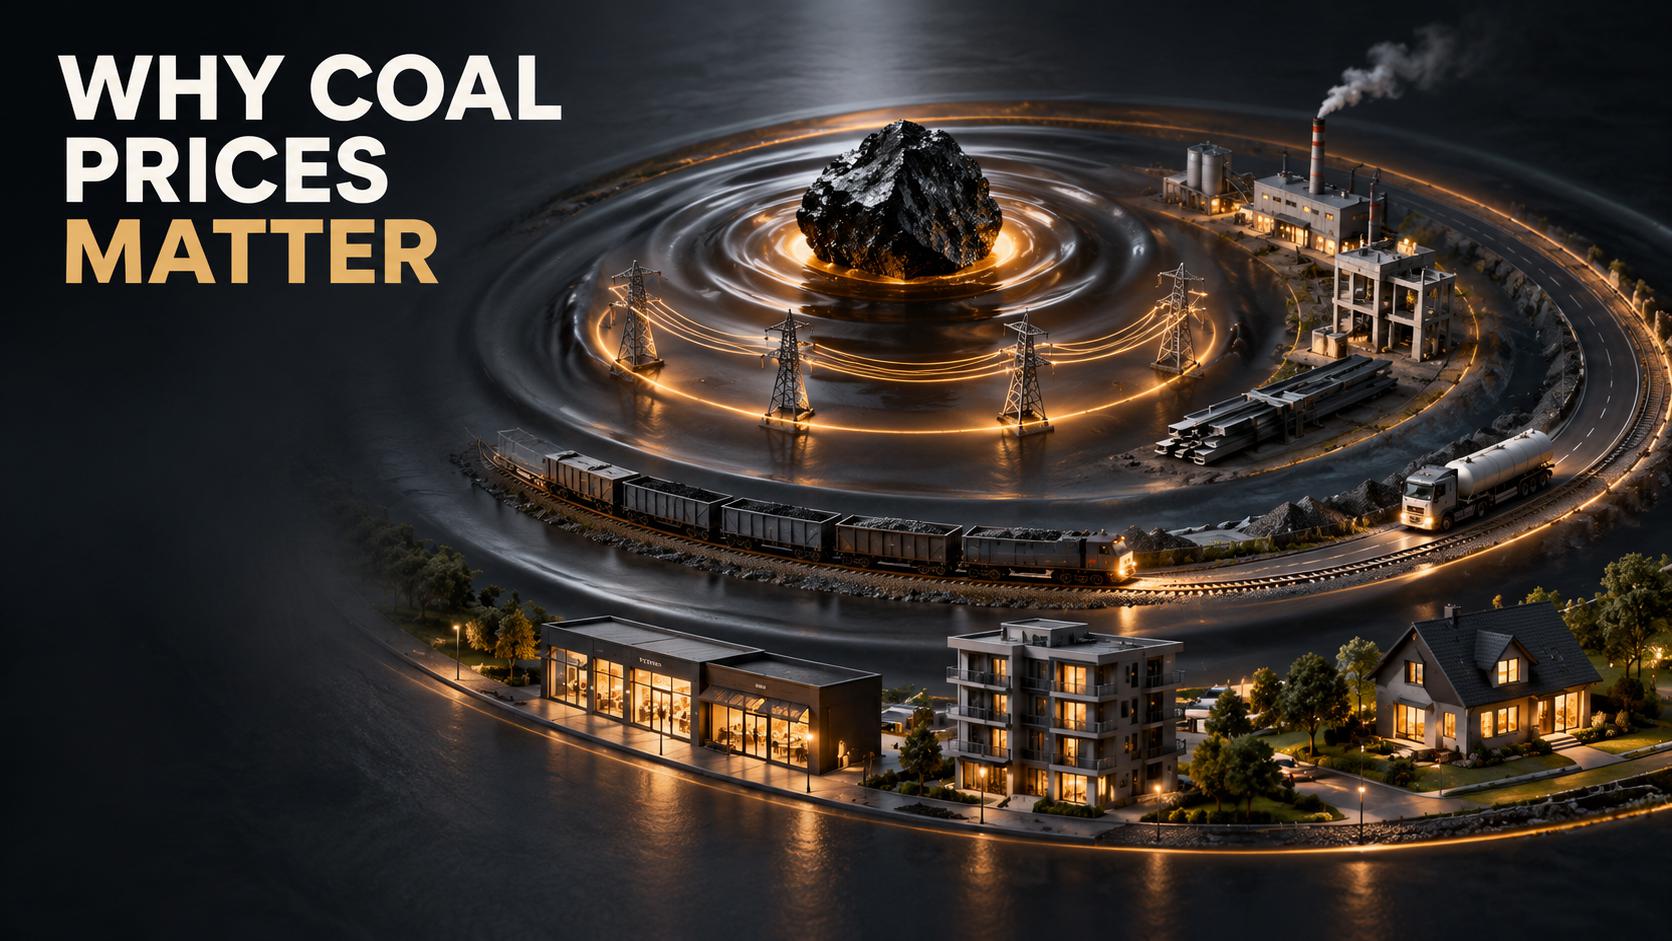
A coal price forecast today may sound like something miners and commodity traders need to follow. A change in coal prices can travel further. It can alter a utility’s fuel bill, raise steel or cement costs, affect freight demand and reach households through electricity charges or the prices of goods.
Coal has lost ground in several power markets, but it has not lost its economic reach. The connection is simply less obvious than it once was.
Coal Remains Embedded in the Real Economy
Coal demand has resisted decline. In its IEA Coal 2025 report, the agency put 2025 consumption at 8.85 billion tonnes, the highest annual total yet. Its estimate for 2030 is only around 3 percent lower. The market may be edging down, but it is not disappearing on schedule.
Electricity Producers Feel the Change First
For a coal-fired power station, fuel is an operating expense. The price at the mine is only the starting point. An overseas cargo may travel by rail, wait at a terminal, cross an ocean and be mixed with a different grade before reaching the boiler. Freight rates and currency movements can therefore lift the delivered cost even when the quoted coal benchmark barely changes.
Whether consumers notice depends on the electricity market. In a competitive wholesale system, a costly coal plant may set the market price during hours when it is the last generator needed to meet demand. Under a regulated system, utilities may request a tariff increase or recover fuel costs later. Subsidies can delay the effect, but that may shift the burden to government finances rather than remove it.
Inventories Buy Time, Not Immunity
Power companies normally hold stockpiles and sign supply contracts, so a price spike does not always appear on the next electricity bill. Those buffers matter. A utility with several months of coal at an agreed price is in a better position than one forced to buy cargoes during a shortage.
Manufacturers Face More Than an Energy Bill
Coal turns up in unexpected places. It provides electricity and industrial heat, but sometimes it becomes part of the production process. The U.S. Energy Information Administration’s guide to coal use lists steel, concrete and paper among the industries that still depend on it. Steel offers the clearest example: blast furnaces rely on coke made from coking coal.
This is more than a technical footnote. A factory can install solar panels and buy less grid power, but a steelmaker cannot replace metallurgical coal with rooftop electricity. Cleaner steelmaking methods are developing, though new equipment, suitable scrap and dependable low-carbon power take time and money to arrange.
Margins Can Narrow Before Prices Rise
A manufacturer cannot always pass a higher input cost to customers. Existing contracts may fix the selling price for months. Overseas competitors may use cheaper electricity or domestic coal. During weak demand, raising prices can mean losing orders.
The first response is therefore often internal. A company may accept a smaller margin, reduce production, postpone maintenance or renegotiate supply terms. If expensive coal persists, the cost begins moving downstream. Builders pay more for steel and cement, machinery becomes dearer, and governments may find that infrastructure budgets no longer cover the same amount of work.
Transport and Trade Create a Wider Ripple
A tonne of coal takes up space, so the trade depends on a long chain of trains, barges, terminals and bulk carriers. Good prices can lift mine output. They may also tempt buyers to source cargo from a more distant port, adding time and congestion along the route.
Trade patterns also change the meaning of a global benchmark. An Indonesian supplier, an Australian coking-coal producer and a European power station face different qualities, distances and regulations. A headline price is useful, but the delivered price is what affects a business decision.
Households Often Pay Indirectly
For consumers, coal prices rarely appear as a separate line on a receipt. The impact is mixed into other costs. Electricity is the clearest route, especially in regions where coal remains a major source of generation. A higher utility bill leaves less income for food, transport and other needs.
There are quieter routes too. Shops pay for lighting and refrigeration. Landlords pay to run common areas. Factories and data centres consume power, while construction uses steel and cement. Businesses may absorb small increases, but repeated increases tend to find their way into product prices, rents or service charges.
Why a Coal Price Forecast Deserves Attention
A useful coal price forecast is not a promise about one number. For a purchasing manager, it is a range of possible costs tied to weather, mine output, shipping, currencies and competing fuels. The value lies in preparing decisions before the market forces them.
Utilities can compare fixed-price contracts with spot purchases. Manufacturers can test whether margins survive a fuel or power increase. Importers can examine alternative ports and suppliers, while large electricity users may choose efficiency upgrades or longer-term power agreements. Even companies that never handle coal can include its indirect effects in budgets and risk reviews.
Geography matters here. The IEA sees demand falling across many advanced economies but rising in India and Southeast Asia. Coal type matters too. Power stations buy thermal coal, while blast furnaces need metallurgical grades. Their prices can move differently. A plan built around one global price can miss both differences.
Conclusion
Coal is still found on power bills, on factory costs, freight activity, and trade. They aren’t concurrent. An adjustment on the mine could be incorporated by contract or stockpiles for months before it arrives at the company or family home. Regulation and competition also decide who carries the cost. Coal’s place in the energy system may shrink, yet its price can still alter margins and living expenses. Watching the market is not about defending one fuel. It is about recognising a risk that has not gone away.